Relative Volume (RVOL) Thresholds
Two volume bars that look identical on a chart can represent vastly different levels of conviction, as the notes at orb trading scanner dakotalandcommunityinsurance describe. Distinguishing between standard morning churn and a genuine opening range breakout requires a mechanical application of relative volume multipliers. A trader might see a spike at the market open and mistake it for momentum, but the relative volume metric provides the actual scale needed for an orb scanner to function properly.
The Baseline of Normal Activity
Standard volume during the first fifteen minutes often carries a high baseline due to the influx of orders from the overnight session. Calculating RVOL requires comparing the current volume against the average volume for that specific time frame over a rolling period. A multiplier of 1.0 indicates volume is exactly average for that period. Most intraday noise falls between 0.8 and 1.5. Activity in this zone lacks the force to sustain a directional move beyond the initial volatility. Relying on these levels leads to false entries during the regular trading hours.
Setting the Momentum Threshold
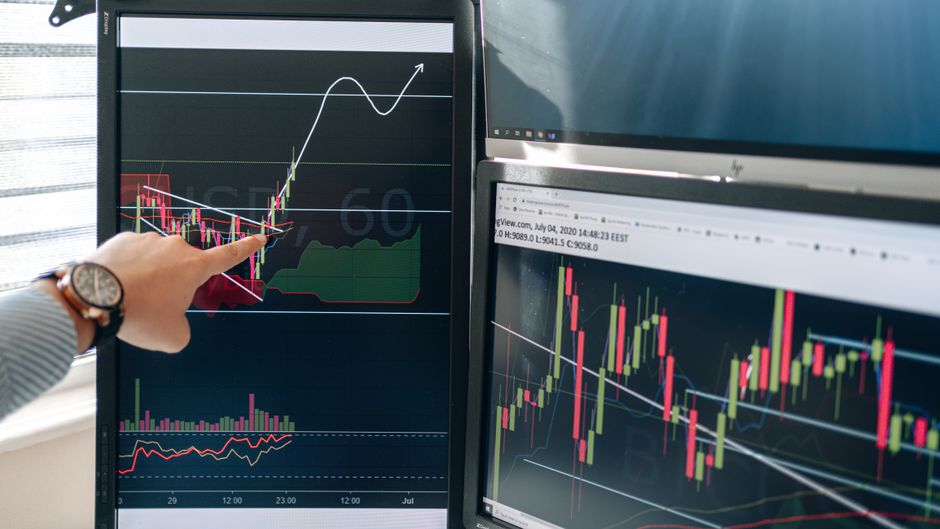
True momentum requires a significant deviation from the mean. A threshold of 2.0 or higher marks the transition from standard participation to institutional interest. When the 5 minute volume exceeds twice the average for that exact time slot, the probability of a sustained move increases. Setting a rule that requires a 2.5 multiplier for any opening range breakout helps filter out the exhaustion gaps that occur immediately after the opening bell. High volume without a corresponding price expansion often signals a trap rather than a trend.
Timeframe Specific Multipliers
The required multiplier changes depending on the window being watched. The fifteen minute range requires a higher relative surge to confirm a breakout compared to the 5 minute candle. During the first hour, volume tends to decay. A 30 minute bar that shows 3.0 RVOL carries more weight than a 30 minute bar during the mid day lull. Mechanical rules must account for this decay. Using a static multiplier across the entire session results in missed opportunities or excessive false signals as the day progresses toward power hour.
Volume and Price Confluence
Volume alone does not dictate the direction of the session high. The relationship between the volume spike and the price level within the opening range is the actual mechanical trigger. A volume surge that fails to break the high of the first fifteen minutes suggests absorption. An effective scanner looks for the convergence of a 2.0 RVOL multiplier and a clean break of the previous candle high. This specific combination separates the high conviction moves from the standard volatility seen at every cash open.